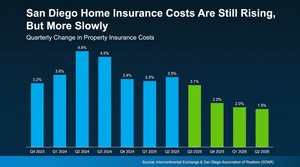
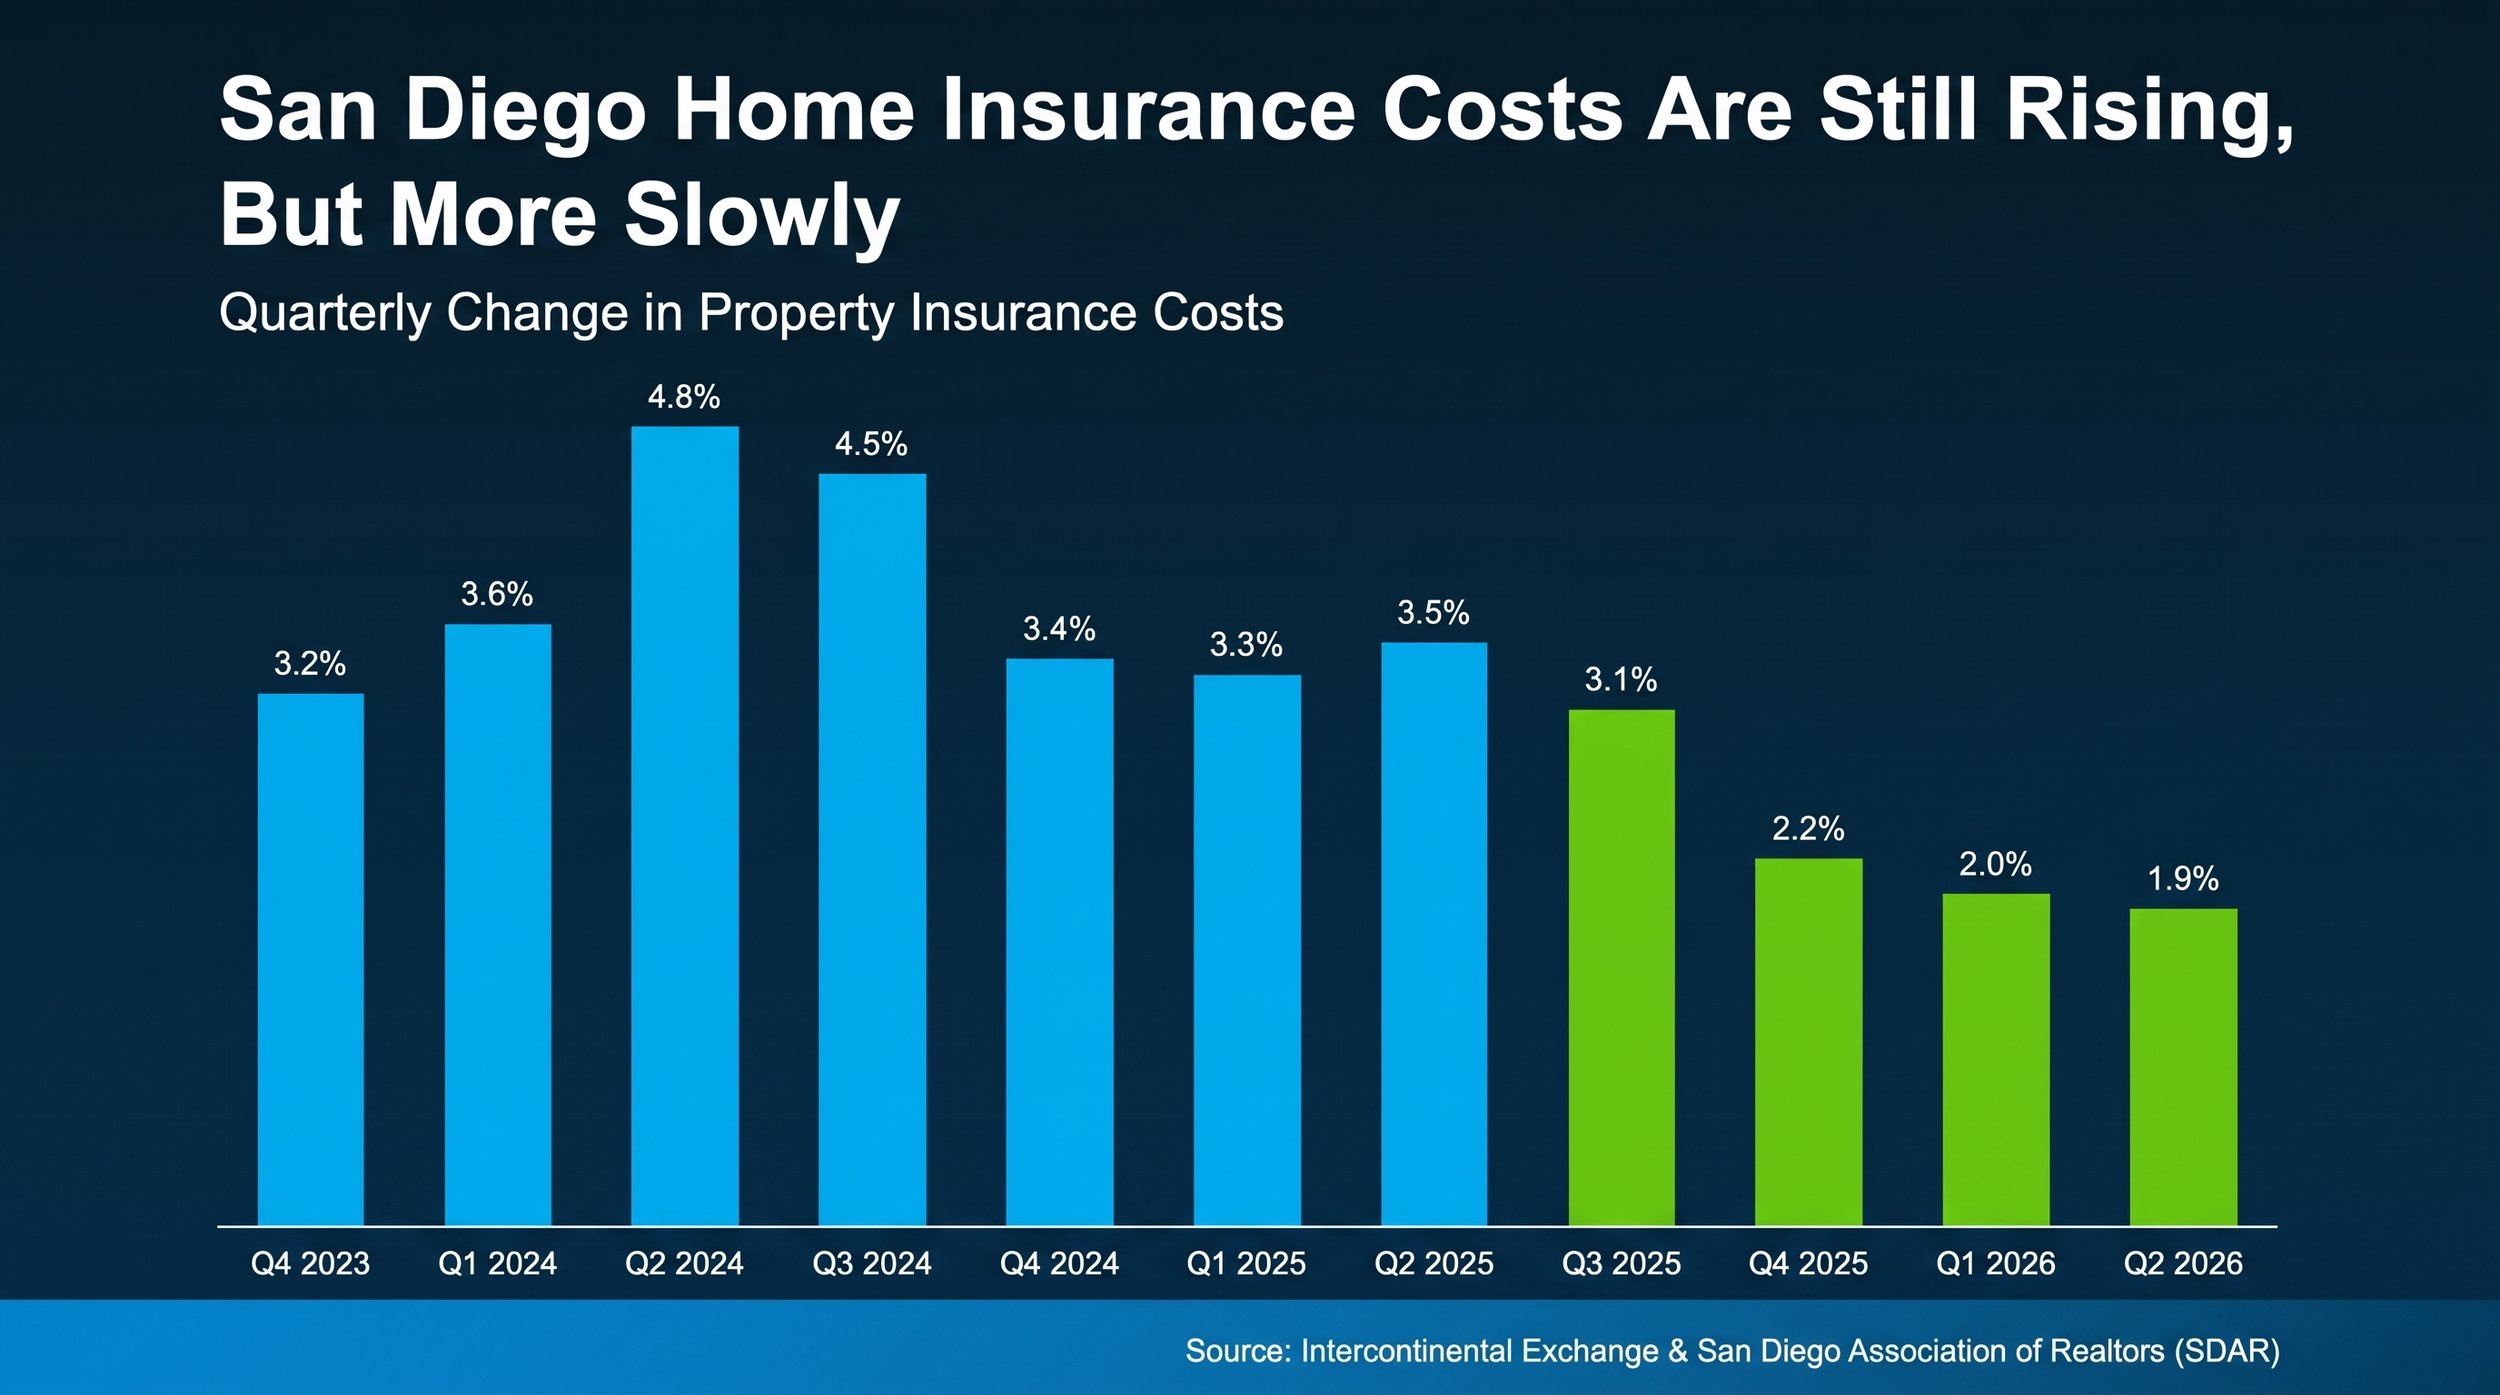
If you own a home in San Diego, you already know that the cost of living in America’s Finest City is steep. Lately, rising home insurance premiums have added another layer of financial stress for local homeowners. Across California, homeowners insurance premiums have surged by 107.6% since 2019. However, a simple strategic move—shopping your policy across different local carriers—can yield massive savings, often putting $400 to $500 back in your pocket annually.
Here is a breakdown of what is happening in the San Diego insurance market in 2026 and the exact steps you can take to lower your bill.
The Data: What San Diego Homeowners Are Actually Paying
Despite headlines about California’s volatile insurance market and the state’s FAIR Plan ballooning to nearly 700,000 policies by mid-2026, San Diego remains remarkably well-insulated compared to the rest of the state.
Average Costs: In 2026, the average annual home insurance premium in San Diego sits between $1,244 and $1,333 for a standard policy with $300,000 in dwelling coverage.
State and National Comparisons: This local average is lower than California’s statewide average of $1,543 per year, which itself remains roughly 55% below the national average.
The Neighborhood Impact: Your exact premium relies heavily on your hyper-local geography. For example, a sample home in the 92110 ZIP code averaged just $1,217 a year, while the exact same house placed in the 92114 ZIP code averaged $1,549 a year—a difference of over 27% purely based on location.
Protecting Your Home in Our Core Neighborhoods
At Dannecker & Associates, we specialize in San Diego’s most sought-after communities, and we know firsthand that real estate—and insurance—is incredibly hyper-local. Because carriers weigh fire risk, coastal proximity, and historic property designations differently, your rates will vary significantly depending on where you buy.
We see these variations every day across the primary neighborhoods we serve:
Coastal Luxury: La Jolla, Del Mar, Solana Beach, Encinitas, Carlsbad, Pacific Beach, and Mission Beach.
Metro & Historic Charms: Downtown San Diego, Point Loma, Coronado, Mission Hills, and Banker’s Hill.
Inland & Urban Core: Allied Gardens, Del Cerro, and University Heights.
Whether you are insuring a sprawling coastal estate in La Jolla or a luxury high-rise condo in Downtown San Diego, actively managing your policy is a crucial part of protecting your real estate investment.
The Move: Stop Settling for Your Renewal Rate
The single best move a San Diego homeowner can make right now is to stop automatically paying their annual renewal and start comparing rates. Because carriers weigh risk differently, the price gap between the cheapest and most expensive insurers in San Diego is staggering.
Recent 2026 data analyzing sample policies in San Diego revealed just how wide this gap can be:
The Low End: Auto Club (AAA members only) quoted an average of $1,088 per year for a standard San Diego home.
The Middle: Mercury Insurance came in at $1,237 per year.
The High End: Farmers Insurance quoted $1,611 per year for the exact same coverage profile.
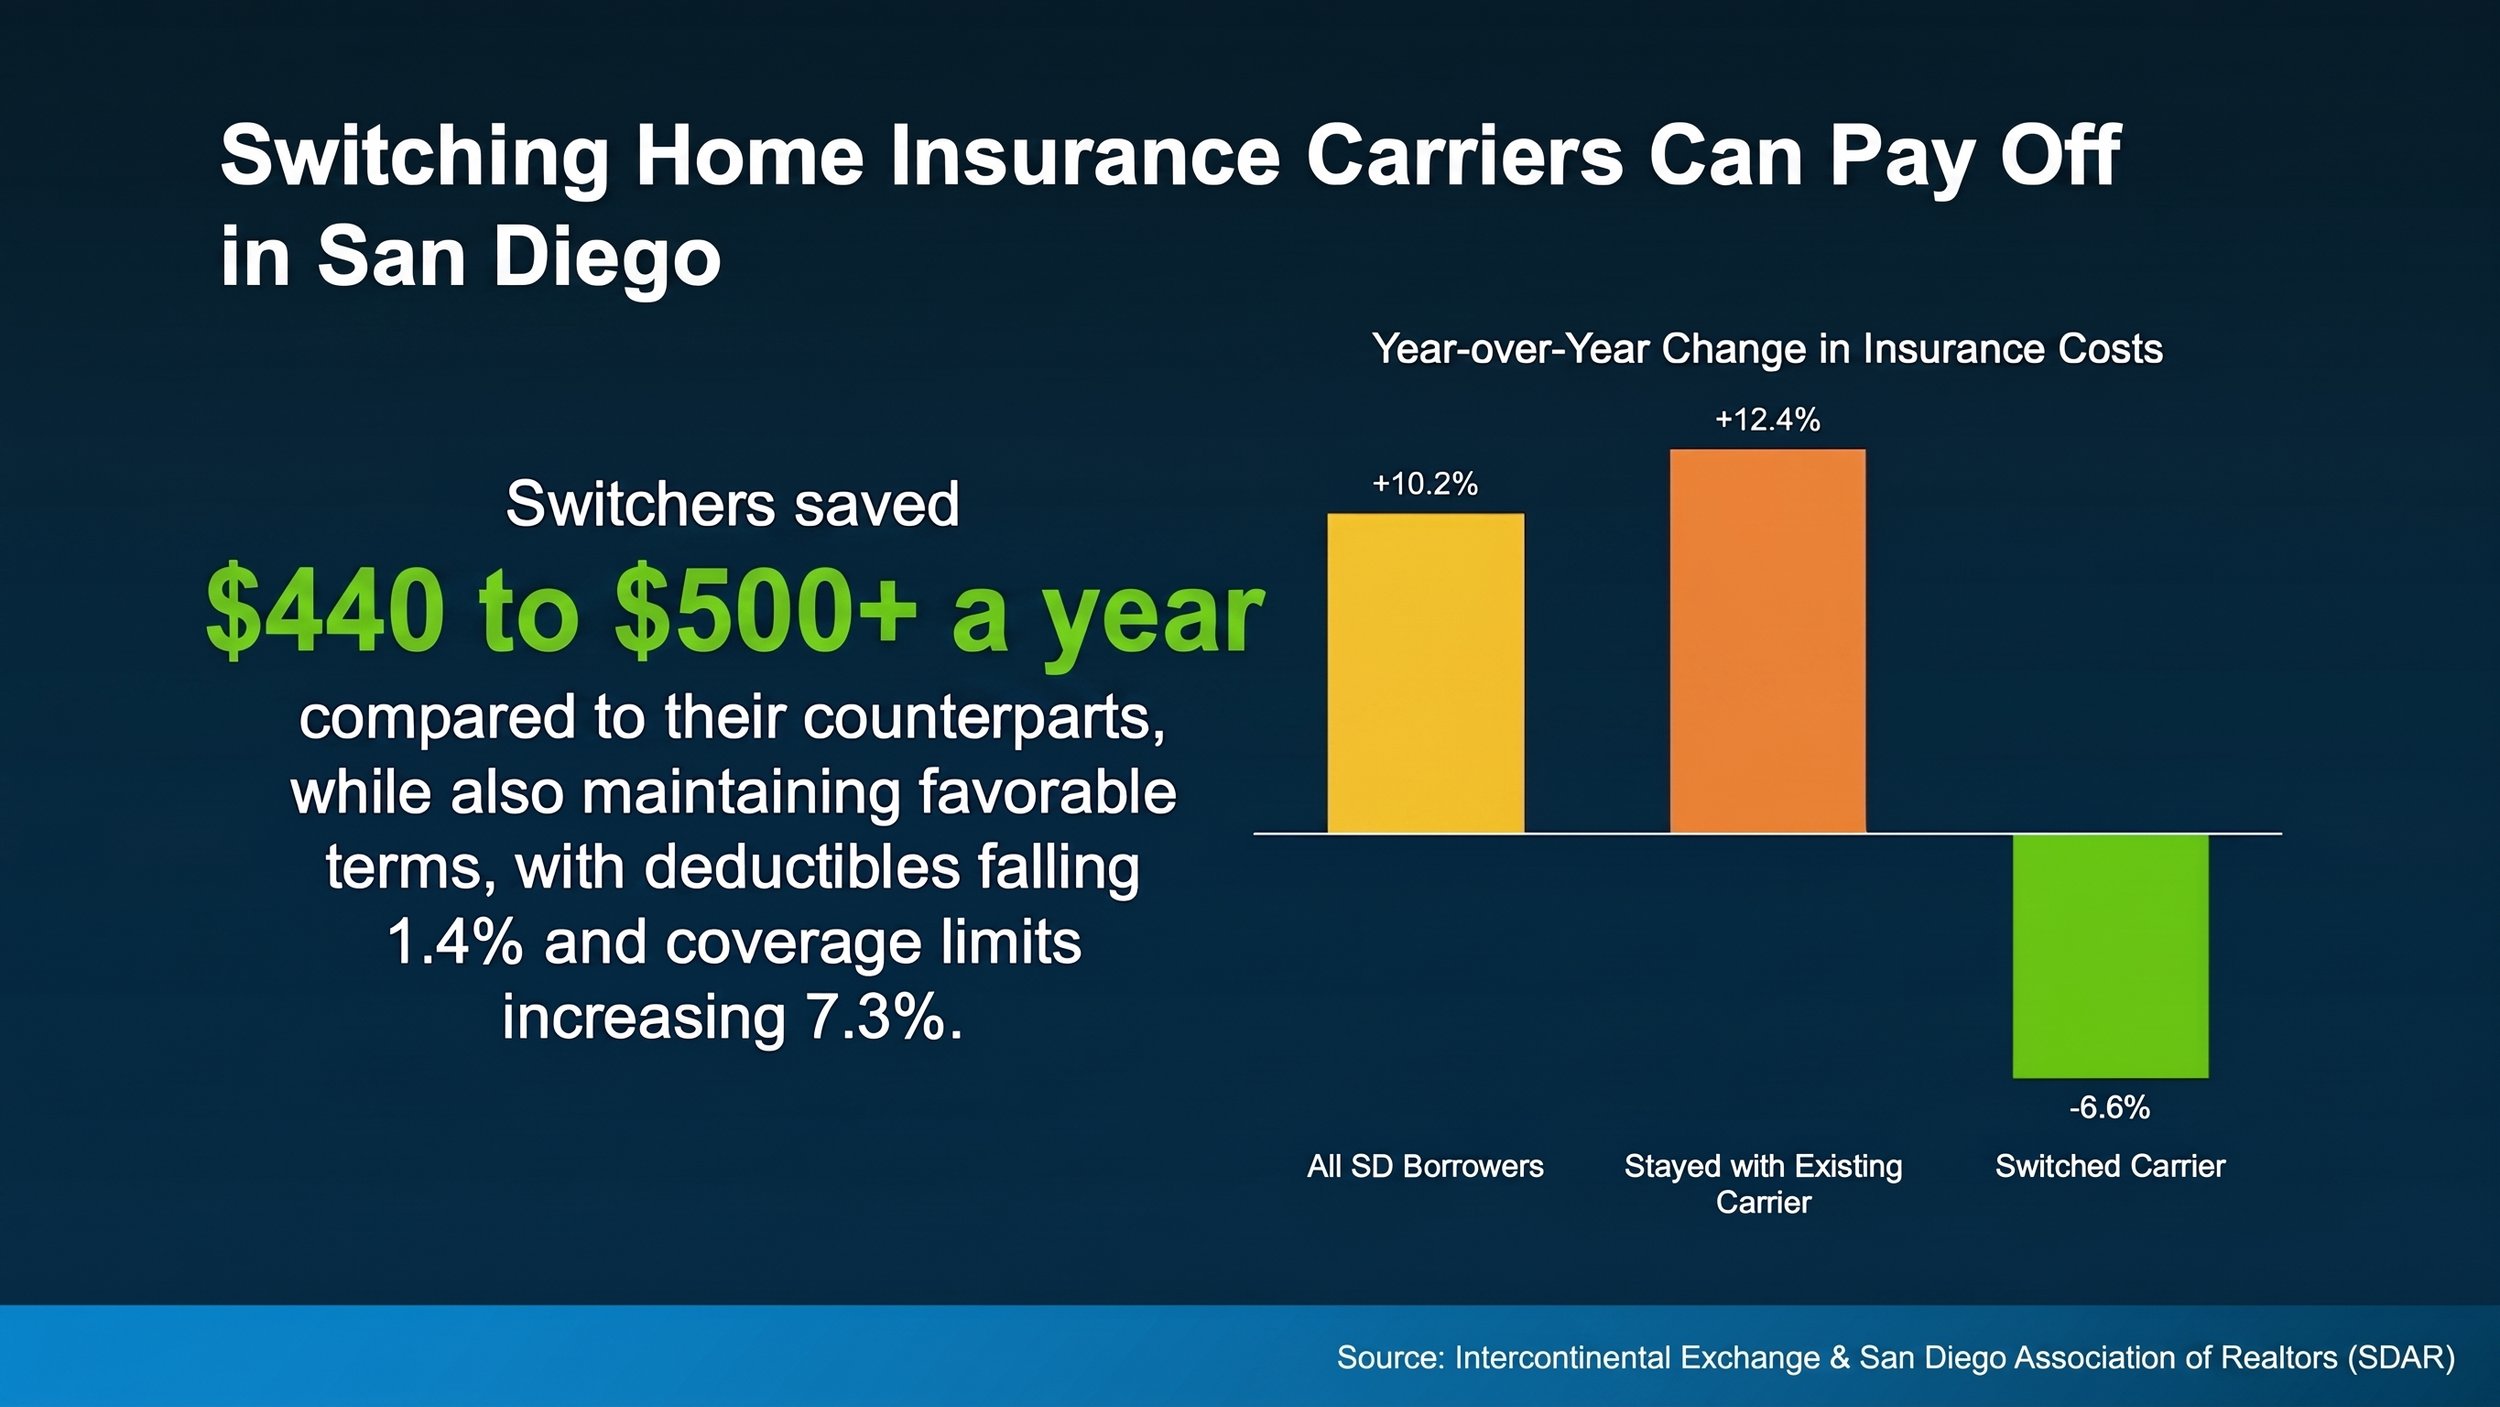
If you were previously insured with a higher-end carrier and switched to one of the most competitive local options, you could realize savings of over $520 a year just by making the switch. This perfectly illustrates how simply shopping the market can easily save you upwards of $440 annually without sacrificing coverage.
Additional Strategies to Lower Your San Diego Premium
If you have already shopped around and are still looking to trim your premium, consider these secondary moves:
Adjust Your Deductible: Many homeowners default to a standard $1,000 deductible. Raising your deductible to $2,500 or higher shifts more of the initial out-of-pocket risk to you in the event of a claim, but it can significantly lower your monthly premium.
Check Your Rebuilding Cost: Policies are designed to cover the cost to rebuild your home, not its current real estate market value. In a high-value market like San Diego, your home’s market value heavily relies on the land it sits on. Ensure your dwelling limit reflects local construction costs (which averaged $478,000 statewide in 2025), rather than over-insuring based on your Zestimate.
Bundle When Possible: If you are using a provider that offers auto insurance in California, bundling your home and auto policies remains one of the most effective ways to trigger a substantial discount.
The California insurance market is in a state of transition. Do not let a fear of the unknown keep you locked into an overpriced policy. Take the time to request quotes from three different carriers this week, and you might just find hundreds of dollars in hidden savings.